President Ratifies Law Ending GST on Overseas Tour Operators, with Refunds Back to 1 October
The law took effect on 19 November, two days after Parliament passed it by 66 votes to none. Tax collected from overseas sellers since 1 October must be returned.
The News
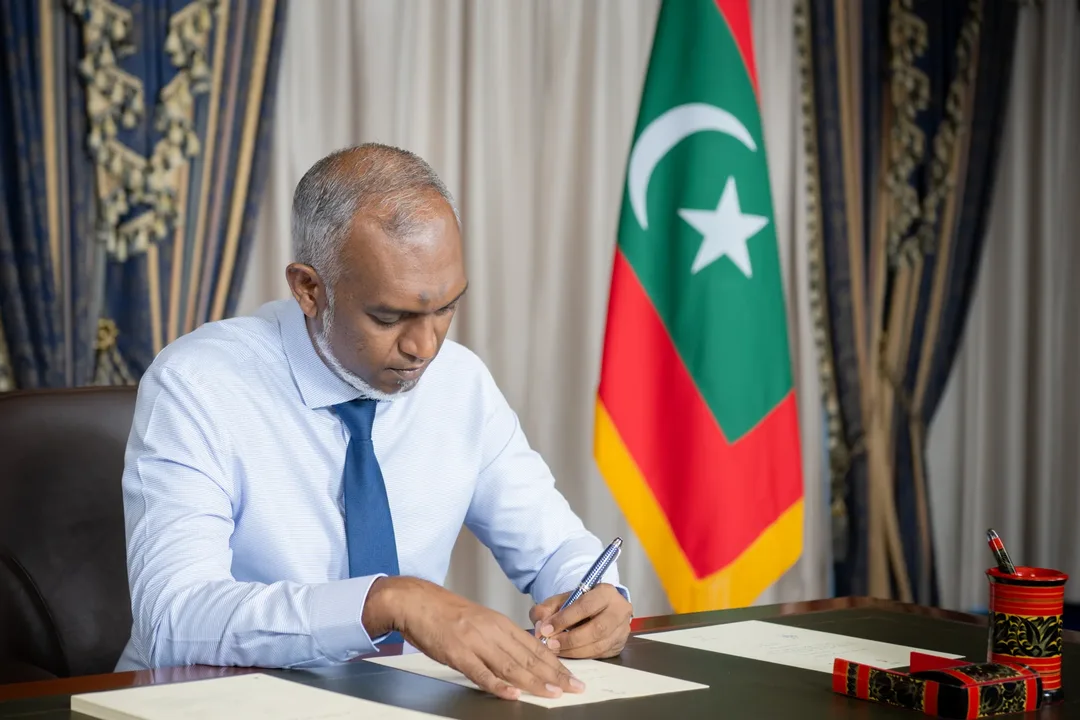
President Mohamed Muizzu has ratified a law that ends the goods and services tax (GST) on Maldives holidays sold by overseas tour operators, travel agents and booking platforms. Tax collected from them since 1 October must be returned.
The President's Office said he ratified the Ninth Amendment to the Goods and Services Tax Act on Thursday, 19 November. The law, numbered 19/2026, was published in the Government Gazette the same day and took effect on publication.
Parliament passed the bill on Tuesday, 17 November. The vote, taken at 11:17, was 66 in favour and none against, with no abstentions, according to the chamber's voting record. Seventy-six members were present and 75 were eligible to vote. Nine did not vote.
Know More
The law says the collection of GST on inbound tourism products, and on agency and booking services, supplied by businesses with no permanent establishment in the Maldives has stopped. That tax had applied since 1 October.
Any GST taken on those sales since 1 October must be returned to whoever paid it, the law says. Suppliers do not have to meet any further obligations under the Act on those sales for the period between 1 October and 19 November.
Changes to the GST regulations must be published in the Gazette within 90 days of the law taking effect.
The law does more than repeal the tax on overseas sellers:
| Change | Detail |
|---|---|
| Tax avoidance | A new section lets the Commissioner General of Taxation disregard a transaction if it gives someone a tax benefit and its only or main purpose was to obtain one |
| Information | The Maldives Inland Revenue Authority (MIRA) can order a registered business to hand over information it holds, to check whether others who should be registered are |
| Registration | From 1 January 2027, businesses must register for GST once their sales in the Maldives pass MVR 1.5 million in 12 months |
| Leaving the register | From the same date, a business can apply to cancel its registration if its sales were under MVR 750,000 in the past 12 months and are expected to stay under that in the next 12 |
The current registration rules stay in force until 31 December. Businesses that are already registered do not have to register again.
Before the final vote, Parliament rejected three amendments to the avoidance section proposed by Mohamed Ibrahim, the Maldivian Democratic Party member for Galolhu North, and seconded by Ibrahim Nazil, the member for Hithadhoo South. One would have required the Commissioner General to act on the advice of an anti-avoidance review panel. Another would have protected a transaction if the taxpayer proved it had a genuine commercial purpose. The third set out who would sit on the panel. The first was defeated by 52 votes to 12.
Step Back
The tax on overseas sellers was introduced by the eighth amendment to the GST Act, which the President ratified on 31 August. It applied the 17% tourism rate to accommodation, meals, transport and other tourism services sold by businesses outside the Maldives, starting on 1 October.
Travel agents and tour operators objected. A government bill to repeal the tax received its first reading in Parliament on 20 October, and members accepted it on 26 October by 43 votes to none, as Maldives Today reported.
The fiscal note attached to that bill, citing MIRA, put the revenue that would be given up at MVR 1,608.5 million. Of that, MVR 1,309.2 million was expected from foreign tour operators and MVR 299.3 million from overseas travel agents.
On 4 November, Tourism and Civil Aviation Minister Mohamed Ameen told a press conference in London that more than 100 major tour operators had registered with MIRA, and that he expected Parliament to pass the repeal within one to two weeks, according to the state broadcaster PSM News.
The President ratified two other tax laws on the same day. One raises the amount taxpayers must pay before appealing a MIRA assessment. The other tightens the limits on interest deductions under the Income Tax Act from 2027.