Parliament Accepts Bill to Double the Upfront Payment for Appealing MIRA Tax Assessments
Taxpayers would have to pay at least half of a disputed assessment, up from a quarter, before going to the Tax Appeal Tribunal. Disputes over tax avoidance and related-party deals would need full payment first.
The News
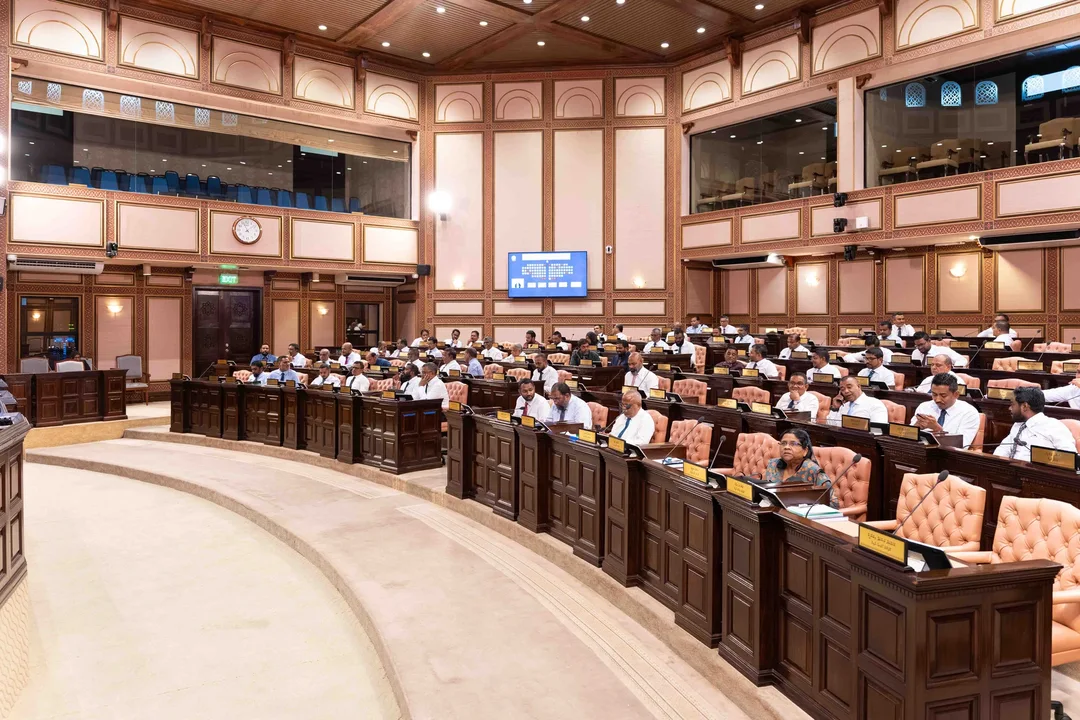
Parliament on Tuesday, 27 October, accepted a government bill that would require taxpayers to pay at least half of a disputed tax assessment before they can appeal it to the Tax Appeal Tribunal. The minimum today is 25%.
The vote, taken at 11:07, was 54 in favour and 11 against, with no abstentions, according to the chamber’s voting record. Seventy-four members were present and 73 were eligible to vote. Eight did not vote.
Ten members of the opposition Maldivian Democratic Party and one independent voted against. The votes in favour came from 53 members of the governing People’s National Congress and one independent, the record shows.
The bill, numbered 20/2026/B-32, amends the Tax Administration Act (Law 3/2010). It is now with Parliament’s Committee on Economic Affairs, the bill’s page shows. It must still clear the committee and a final vote, then be ratified and published in the Government Gazette, before it takes effect.
Know More
Funadhoo MP Mohamed Mamdooh submitted the bill on behalf of the government. It received its first reading on 20 October.
Under the bill, a taxpayer appealing an assessment by the Maldives Inland Revenue Authority (MIRA) would first have to pay MIRA at least 50% of the amount in dispute. The bill sets no upper limit on that payment.
The whole disputed amount would have to be paid before an appeal in four kinds of case. Two come from the Income Tax Act: arrangements caught by its general anti-avoidance rule, and deals between associated persons on terms that are not at arm’s length. The other two come from the Goods and Services Tax (GST) Act. One covers supplies of goods or services to related parties. The other refers to a provision in the Act’s rules on valuing supplies.
Both percentages would be worked out without counting any fines or interest owed on the disputed amount, as the current 25% is. Nothing would have to be paid to appeal an assessment to the extent that it reduces a tax loss carried forward under the Income Tax Act. The Act already contains that exemption, and the bill keeps it.
The government’s statement of purpose, attached to the bill, refers only to setting out the cases that would require full payment. It does not mention the rise from 25% to 50%. The bill document published by Parliament contains no estimate of its effect on revenue.
The bill would also require any changes to regulations to be published within 90 days of it taking effect.
Step Back
The Act’s second amendment, issued in September 2019, set the payment at a minimum of 30% of the disputed tax. The third amendment, issued in December 2020, lowered it to 25%, according to MIRA’s translations of the two laws.
The tribunal must decide an appeal within 180 days of filing, a period its members can extend by up to 90 days. Where an objection or appeal finds that a taxpayer owes less than MIRA assessed, the difference is treated like any other overpaid tax, under the Act as consolidated by MIRA. The bill does not change those rules.
The Act was last amended on 31 August, when President Mohamed Muizzu ratified a fourth amendment. It strengthened MIRA’s audit, investigation and recovery powers and set a code of conduct for tribunal members, the President’s Office said.
The bill is one of three government tax bills that received their first reading on 20 October. On 26 October, Parliament accepted the bill to repeal GST on overseas tour operators and booking platforms with no votes against, as Maldives Today reported. The third bill amends the Income Tax Act.
The Committee on Economic Affairs took up the tax administration bill later on 27 October. Its agenda was to set a deadline for its review and to decide whether to seek public comment and which bodies to consult.
The Record
- People’s Majlis: voting record for the acceptance of bill 20/2026/B-32, 27 October 2026
- People’s Majlis: bill 20/2026/B-32 and its status
- The bill, its statement of purpose and comparison table (Dhivehi)
- People’s Majlis: 10th sitting of the third session, 27 October 2026
- People’s Majlis: Committee on Economic Affairs, 22nd meeting of 2026
- Committee on Economic Affairs: agenda for 27 October 2026 (Dhivehi)
- MIRA: Tax Administration Act, consolidated translation
- MIRA: Second Amendment to the Tax Administration Act (Law 13/2019)
- MIRA: Third Amendment to the Tax Administration Act (Law 27/2020)
- MIRA: Income Tax Act, consolidated translation (sections 66 and 67)
- President’s Office: fourth amendment to the Tax Administration Act ratified, 31 August 2026